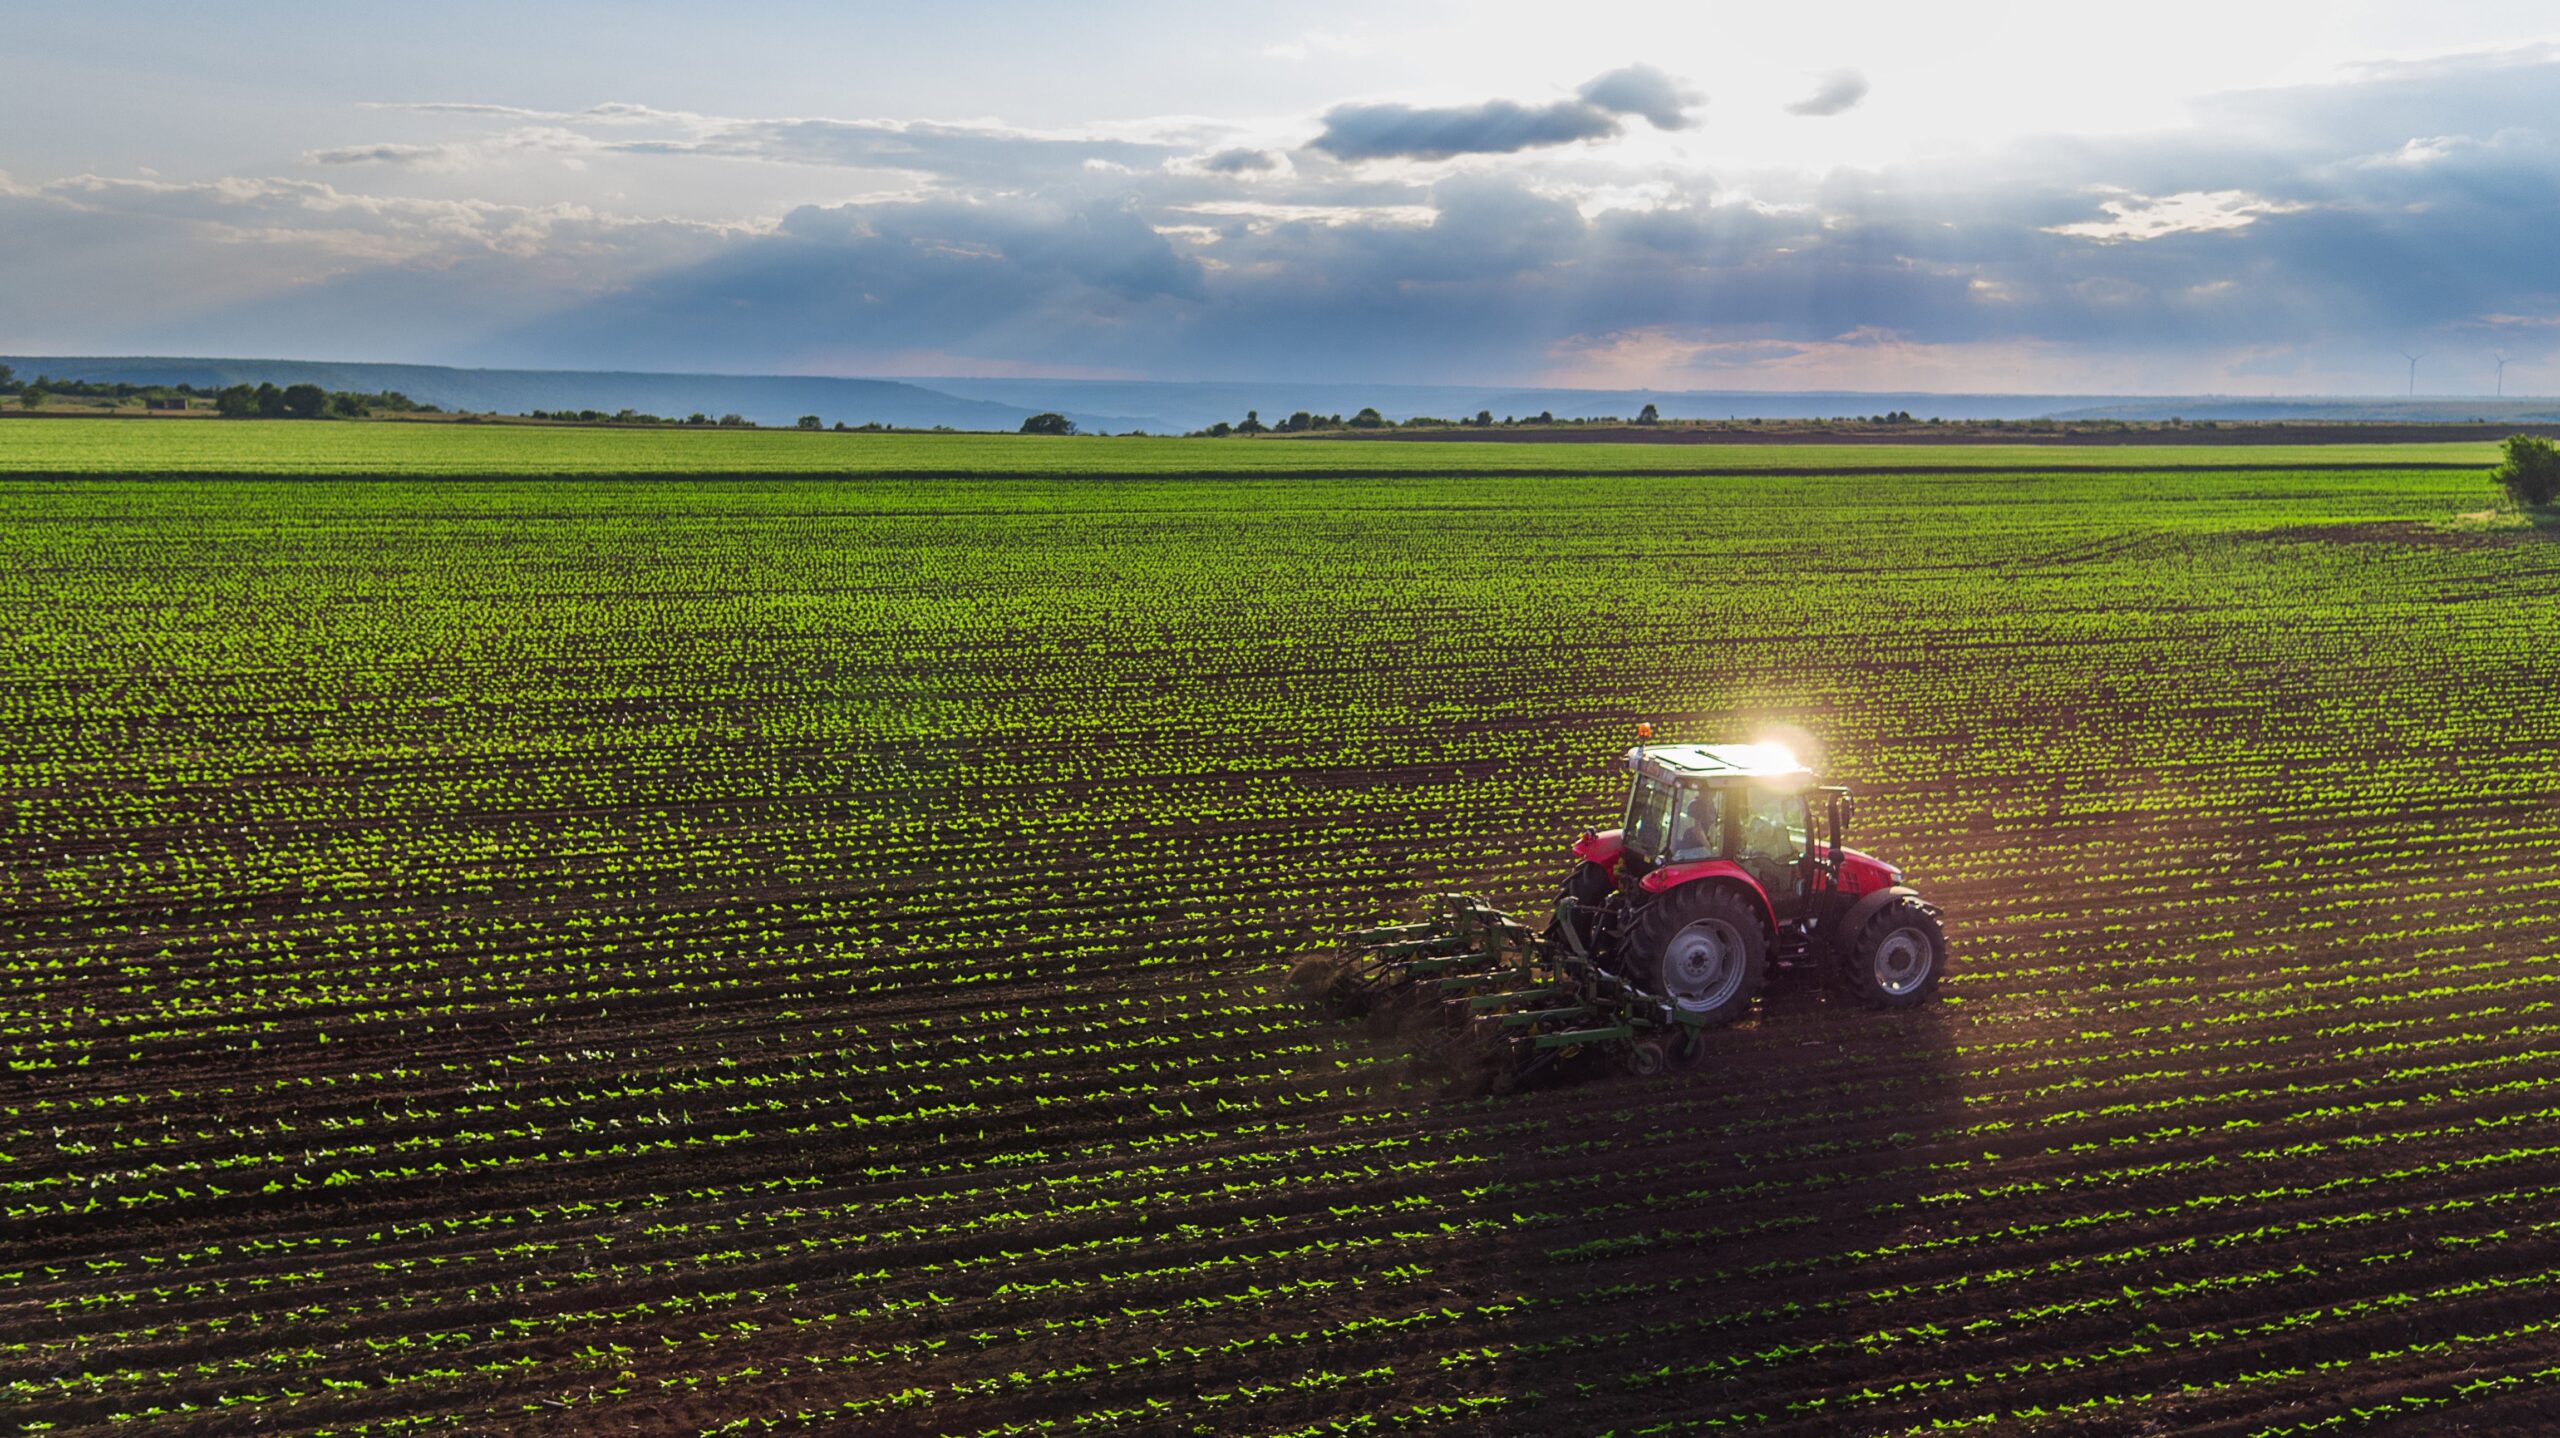
Discover the Single-Family Housing Guaranteed Loan Program, provided by the United States Department of Agriculture (USDA). This program enables qualified borrowers to acquire homes in eligible rural areas, as determined by the rural housing program’s criteria. To participate, borrowers should be aware that an upfront guarantee fee and an annual fee are imposed. If you want to apply for this program, we encourage you to contact one of our licensed loan officers immediately. They will be more than happy to assist you throughout the application process.
USDA Streamline Refinance Transactions
The United States Department of Agriculture (USDA) offers three refinance programs for qualified borrowers. These are a non-streamline refinance, a streamline refinance, and a streamline-assist. Borrower and household income limit qualifications do apply in each case. Contact one of our licensed loan officers today to apply!
Benefits of USDA Loans
- 100% Financing – you can buy a home with no down payment.
- Low Fixed Rate Mortgage Options.
- Government-insured.
- Simple Loan Process.
- There is No Prepayment Penalty.
Down Payment Assistance (DPA) programs assist homebuyers by providing additional funds from a third party for purchase transactions. The funds help cover the down payment and/or closing costs. DPA is either in the form of a gift/grant or in the form of a loan secured by the property (second mortgage). DPA is typically provided by the State Housing Authority or a municipality like a city or county. DPA second mortgage loans may either be forgivable, deferred (no payments on the loan, but the principal will be paid back at a time in the future), or repayable (with monthly payments).
DPA programs have their own set of requirements that must be met. Some of those requirements may include income limits and the need to be a first-time homebuyer. The requirements differ based on the program.
Homebuyers usually work with their lenders to obtain DPA funds. Loan Officers at Success Mortgage Partners can help you identify DPA programs for which you may qualify.
A Non-QM (Non-Qualified Mortgage) loan is a type of mortgage that does not meet the standard criteria set by government-sponsored enterprises (GSEs) such as Fannie Mae or Freddie Mac. These loans fall outside the guidelines established by the Consumer Financial Protection Bureau (CFPB) for Qualified Mortgages (QMs).
The main difference between QM and Non-QM loans lies in the level of risk and borrower qualification standards. QM loans are designed to be safer for lenders and borrowers, with features such as a maximum debt-to-income ratio, limitations on fees, and certain underwriting requirements. On the other hand, Non-QM loans are more flexible but come with higher risk for both the lender and the borrower.
Here are some key characteristics of Non-QM loans:
- Alternative Documentation: Non-QM loans may allow alternative documentation forms, such as bank statements, to verify income instead of traditional W-2 forms or tax returns.
- Higher Debt-to-Income Ratios: Non-QM loans may accept borrowers with higher debt-to-income ratios than what is allowed for QM loans.
- Interest-Only Payments: Some Non-QM loans may offer the option for interest-only payments for a certain period, providing more flexibility for borrowers.
- Unique Property Types: Non-QM loans may be used for unique or non-standard property types that do not conform to traditional mortgage guidelines.
- Credit Issues: Borrowers with credit issues, such as recent bankruptcies or foreclosures, may be eligible for Non-QM loans when they would not qualify for QM loans.
I have great credit and looking for a low down-payment loan.