Explore Mortgage Options in Marion, AL
Are you considering purchasing a home in Marion, AL? Understanding your mortgage options is crucial to making an informed decision. This guide provides insights into various mortgage types available to potential homebuyers in the area, making it easier to find the right path to homeownership.
Conventional Loans
Conventional loans are a popular option among homebuyers. These loans are not backed by any government program and typically require a down payment of at least 3% for eligible borrowers. They can be used for purchasing primary residences, second homes, and investment properties.
Because they’re not government-insured, conventional loans may require more stringent credit and income qualifications. However, for those with good credit, these loans might offer favorable terms. Remember, mortgage insurance is generally required if your down payment is less than 20%. This protects lenders against defaults and can affect your monthly payment.
FHA Loans
The Federal Housing Administration (FHA) offers FHA loans that are specifically designed for low-to-moderate-income buyers. These loans allow down payments as low as 3.5%, making them an attractive option for first-time buyers in Marion.
One advantage of FHA loans is their flexibility regarding credit history. Borrowers with less-than-perfect credit may still qualify, though an upfront mortgage insurance premium (MIP) and an annual MIP will apply. FHA loans require compliance with certain guidelines, so understanding these requirements is essential before applying.
VA Loans
For eligible veterans, active-duty service members, and certain members of the National Guard and Reserves, VA loans provide excellent financing options. VA loans offer the benefit of no down payment, making homeownership more accessible.
These loans do not require private mortgage insurance (PMI), which can save you money on monthly payments. A funding fee is typically applicable, which may be financed into the loan. As with FHA loans, it’s essential to meet specific eligibility criteria. The VA loan program helps many service members achieve their dream of owning a home in Marion.
USDA Loans
The United States Department of Agriculture (USDA) offers loans aimed at encouraging homeownership in rural areas, including Marion. Qualified borrowers can access 100% financing, eliminating the need for a down payment.
USDA loans are available to individuals and families and come with low mortgage insurance costs. To qualify, borrowers must meet income limits and ensure the property is located in a designated rural area. This program is a fantastic way for eligible buyers to step into homeownership without the financial burden of a traditional down payment.
Jumbo Loans
For those looking to purchase properties that exceed the current conforming loan limit set annually by the FHFA, jumbo loans are available. These loans are suitable for higher-priced homes but come with stricter credit score and income documentation requirements compared to conventional loans.
Jumbo loans are not backed by government-sponsored enterprises like Fannie Mae or Freddie Mac and are typically held by the originating lender or sold to private investors. This means they follow specific underwriting guidelines determined by the lender. If you’re considering a high-value property in Marion, exploring jumbo loans could be beneficial.
Key Takeaways
- Assess your financial situation to determine which loan options best suit your needs.
- Consider working with a trusted mortgage advisor to navigate the various program requirements.
- Being informed about the differences between loan types helps empower your decision-making process.
Marion, AL, offers diverse mortgage options catering to various buyer needs. Whether you’re a first-time homebuyer or looking to purchase a higher-priced property, understanding these options is essential. If you’re interested in exploring these mortgage options tailored to your unique circumstances, reach out to Christopher for a personalized consultation — rates are not guaranteed and are subject to change based on your individual qualifications and market conditions.
Christopher Shrader NMLS# 1695950 | Success Mortgage Partners NMLS# 130562 | Equal Housing Lender | Licensed in Delaware. This content is for informational and educational purposes only and does not constitute financial, legal, or tax advice, nor is it a commitment to lend. All loans are subject to borrower qualifications, including credit approval, income verification, and property evaluation. Rates, terms, and APR are subject to change without notice. Created: October 19, 2026
Low-down-payment amounts are general minimums available under certain loan programs for eligible borrowers; availability depends on program requirements and borrower qualifications and is not guaranteed.
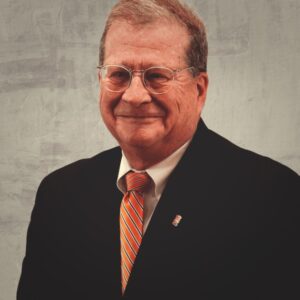
Work with Chris Shrader
Senior Loan Officer
NMLS #1695950